

The Dutch healthcare system is renowned for its high-quality services and universal coverage. It seamlessly blends public and private elements to ensure that all residents have access to essential medical care. For expatriates and visitors, understanding the nuances of this system is crucial to navigating healthcare services effectively.
1. Overview of the Dutch Healthcare System
The Dutch healthcare system operates on principles of accessibility and quality. All residents are required to obtain health insurance from private insurers, which are mandated to accept all applicants. This structure ensures that everyone, regardless of their health status, has access to necessary medical services. The system is primarily funded through a combination of income-based taxes and insurance premiums. The government plays a pivotal role in regulating insurers and healthcare providers to maintain service standards and control costs.
2. Health Insurance
Basic Health Insurance (Zorgverzekeringswet – Zvw)
Under the Zorgverzekeringswet (Zvw), all residents must purchase basic health insurance from private insurers. This insurance covers essential medical services, including visits to general practitioners (GPs), hospital care, and prescribed medications. Insurers are obligated to offer this standard package at a fixed price, ensuring uniformity in coverage. The average monthly premium for basic health insurance is approximately €135.
Long-Term Care Insurance (Wet langdurige zorg – Wlz)
The Wet langdurige zorg (Wlz) provides coverage for long-term care needs, such as nursing home care and assistance for individuals with chronic conditions. This insurance is funded through income-based contributions and is automatically provided to all residents.
Choosing Health Insurance: Considerations for Expats
Expatriates moving to the Netherlands are required to obtain Dutch health insurance within four months of arrival. When selecting a policy, it’s essential to compare different insurers, considering factors such as premium costs, coverage options, and customer service quality. Some insurers offer policies tailored for non-Dutch speakers, providing services and documentation in English. Additionally, individuals with lower incomes may be eligible for a healthcare allowance (zorgtoeslag) to offset insurance costs.
Health Insurance for Temporary Visitors
Visitors staying in the Netherlands for less than a year are not required to obtain Dutch health insurance. However, they must have adequate health coverage, such as the European Health Insurance Card (EHIC) for EU residents or international health insurance plans for non-EU visitors. It’s advisable to verify that the insurance policy covers medical expenses incurred in the Netherlands.
If you’re looking to compare health insurance plans and find the best option for your needs, check out this health insurance comparison tool.
3. What Does Health Insurance Cover?
The basic health insurance package in the Netherlands includes:
- General Practitioner (GP) Consultations: Visits to a GP for general health issues.
- Hospital Care: Inpatient treatments, surgeries, and specialist consultations.
- Prescription Medications: Medications prescribed by a healthcare provider.
- Maternity Care: Prenatal and postnatal care, including home nursing support after childbirth.
- Mental Health Services: Access to psychologists and psychiatrists for mental health concerns.
While the basic package in the Dutch healthcare system is comprehensive, it does not cover certain services such as dental care for adults, physiotherapy, or alternative treatments. For these services, individuals can opt for supplementary insurance at an additional cost.
4. Healthcare Services
| Healthcare Service | Description | Access Requirements | Coverage by Basic Insurance |
| Primary Care (General Practitioners, Hospitals, Specialists) | General Practitioners (GPs) are the first point of contact for medical concerns. They provide referrals to specialists. | Patients typically need a GP referral to see a specialist. Hospitals provide emergency services without a referral. | Yes, GP visits and hospital treatments are covered. Some specialist treatments may require co-payments. |
| Specialized Care (Managing Chronic Diseases) | For chronic conditions or cardiovascular diseases, integrated care teams develop personalized treatment plans. | Referral from a GP is often required for specialist consultations. Chronic care is coordinated through integrated healthcare programs. | Yes, chronic disease management is included, but specific treatments might need additional insurance or co-payment. |
| Dental Care (Specifics and Reimbursements) | Dental care for those under 18 is covered by basic health insurance. Adults must purchase supplementary insurance for dental services. | Basic health insurance covers dental care for children under 18. Adults must opt for additional insurance for routine dental care. | No, only emergency dental care for adults is covered. Children under 18 receive full coverage. |

5. Medications and Pharmacies
Types of Pharmacies: Pharmacies (apotheken) in the Netherlands are well-distributed and provide prescription and over-the-counter medications. Pharmacists also offer consultations regarding medication usage and potential side effects.
After-Hours Pharmacies: For urgent medical needs outside regular hours, after-hours pharmacies (dienstapotheek) are available. These pharmacies ensure that individuals have access to necessary medications at any time.
6. Practical Tips for Users
Finding a General Practitioner and Scheduling Appointments
Registering with a local GP is essential, as they coordinate all medical care. It’s advisable to choose a GP close to your residence. Appointments can typically be scheduled by phone or online. For non-urgent issues, it’s recommended to plan ahead, as same-day appointments may not always be available.
What to Do in Case of a Medical Emergency
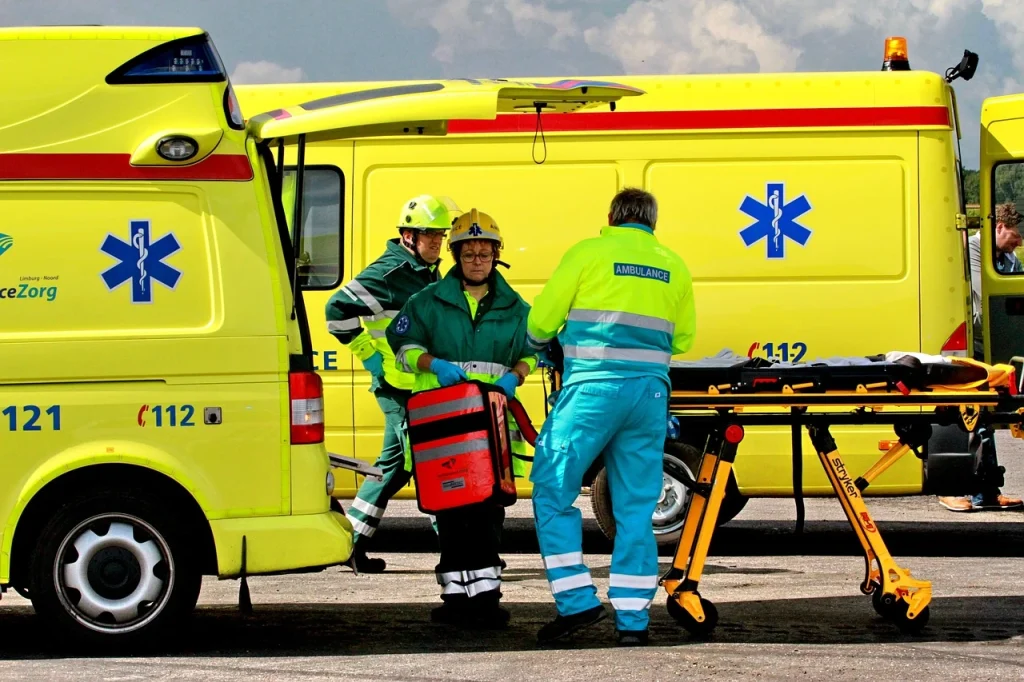
In emergencies, dial 112 for immediate assistance. For urgent but non-life-threatening situations, contacting your GP’s office during working hours or the out-of-hours medical service (huisartsenpost) is appropriate.
To Finish
The Dutch healthcare system is one of the most efficient and accessible in the world. Whether you are an expatriate settling in the country or a visitor needing temporary health coverage, understanding how the system works will help you navigate it with ease. If you are moving to the Netherlands, make sure to arrange your health insurance on time to ensure seamless access to healthcare services.
If you’re planning to move to the Netherlands, it’s essential to understand the cost of living to better manage your budget. Check out this comprehensive guide on the cost of living in Amsterdam.
FAQs
1. Do I need Dutch health insurance if I already have international health coverage?
Yes, if you are a resident or working in the Netherlands, you must take out Dutch health insurance, even if you have international coverage. Exceptions apply to certain temporary visitors, students, and diplomats, but in most cases, local insurance is mandatory.
2. How do I find a general practitioner (GP) in the Netherlands?
To register with a GP, you can search for one in your area and contact their practice to check for availability. It’s recommended to register as soon as possible, as GPs play a crucial role in the Dutch healthcare system, acting as the first point of contact for medical care.
3. Can I visit a specialist directly, or do I need a referral?
In the Dutch healthcare system, you generally need a referral from your general practitioner (GP) to see a specialist. Direct access is only possible for certain services like dental care, physiotherapy (if covered by additional insurance), and emergency treatments.